How Insurance Claims with Mobile Apps Are Transforming Claims Processing
Jaideep Sharma - Director of Operations | October 01, 2026
- Mobile claims applications move the insurance claims process closer to the point of loss. Policyholders can report incidents, submit photos and documents, communicate with insurers, and track claim status from a mobile device.
- The biggest value comes from connecting the app to claims management software. A mobile interface alone does not automate insurance claims management; integrated workflows can route claims, capture information, trigger tasks, and give adjusters the data they need.
- AI can support or automate different parts of claims processing. AI-assisted workflows keep claims professionals involved in decisions, while straight-through processing can handle suitable, predictable claims with limited human intervention.

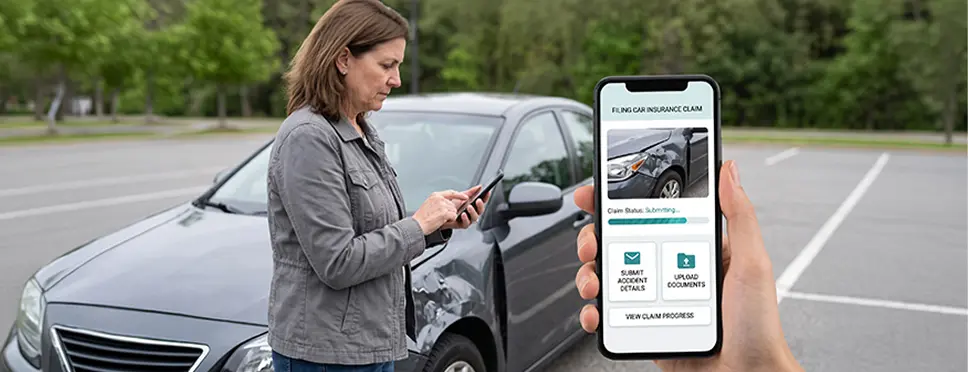
An insurance claim often begins at an inconvenient moment: after an accident, property damage, theft, or another unexpected loss. The first challenge for an insurer is therefore to make it easy for the policyholder to provide the right information while making that information useful to the people responsible for handling the claim.
Mobile applications can bring those two needs together. A policyholder can report an incident, photograph damage, upload documents, answer questions, and receive claim updates without relying entirely on phone calls or paper-based exchanges.
For insurers, the value extends beyond the mobile experience. When an app is connected to claims management software, information collected during the first interaction can become part of the insurer's existing workflow. That creates a path toward more connected insurance claims processing, where digital intake, automation, analytics, and human expertise work together.
The Evolution of Insurance Claims Processing
Insurance claims have moved through three distinct stages as insurers have adopted new ways to collect, manage, and process information:
Manual claims handling
Claims once relied heavily on phone calls, paper forms, physical documents, and manual data entry. Policyholders had limited visibility into claim progress, while adjusters spent significant time collecting and organizing information.
Digital claims management
The adoption of claims management software brought claim records, documents, workflows, and communications into digital systems. Insurers gained greater visibility into claims, while automated workflows reduced repetitive administrative tasks.
Mobile and connected claims
Mobile applications moved digital claims processing closer to the point of loss. Policyholders can report incidents, capture photos, upload documents, and receive updates from their phones. When the app connects with insurance claims software, this information can flow directly into the insurer's claims workflow.
This progression matters because digitizing one task does not necessarily improve the entire claims journey. The greater opportunity comes from connecting the policyholder's mobile experience with the systems and workflows that actually process the claim.
What is an Insurance Claims Mobile App?
An insurance claims mobile app is a customer- or adjuster-facing application designed to support activities associated with reporting, documenting, managing, and tracking an insurance claim. Depending on the insurance product and claims workflow, the application may support:
Digital first notice of loss (FNOL)
Policyholders can report an incident and provide the information needed to begin a claim.
Photo and video capture
Customers can document vehicle, property, or other damage from the point of loss.
Document submission
Receipts, estimates, reports, and other claim-related documents can be uploaded directly.
Claim tracking
Policyholders can view claim status, outstanding actions, appointments, and updates.
In-app communication
Messaging and notifications can connect policyholders with claims teams.
Adjuster workflows
Field personnel can access claim information, record observations, upload evidence, and update tasks while working outside the office.
System integration
APIs can connect the app with claims management software, policy administration systems, CRM platforms, payment systems, document repositories, repair networks, analytics platforms, and AI services.
The application becomes more useful when it is connected to the insurer's existing insurance claims management software. Without that connection, employees may still have to transfer information from the mobile application into other systems manually.
“The National Association of Insurance Commissioners (NAIC) specifically identifies mobile apps and photo-based claims tools as examples of insurtech that can allow consumers to submit documents and track claim progress.”
Why Insurers are Adopting Mobile Claims Applications
Claims can involve a large amount of information, including policy details, photographs, estimates, documents, adjuster notes, communications, and payment information. If that information arrives through disconnected channels, claims teams have to spend time gathering and organizing it before they can act.
A mobile application can move some of that information capture to the beginning of the process.
For policyholders, this can mean fewer steps to report a loss and clearer access to claim information. For adjusters and claims teams, information submitted through a structured digital workflow can be available earlier and in a more usable format.
Research on claims modernization describes a model in which customers can initiate a claim through a mobile app or other digital channel, while the app connects with the insurer's claims management system and third-party data sources. - McKinsey & Company
That connection is what makes claims processing automation possible at the workflow level. A mobile form can collect information, but integrated systems can use that information to trigger tasks, route claims, request missing documents, and support subsequent stages of processing.
Key Features of An Insurance Claims Mobile App
The features an insurer needs will depend on its products and claims workflows. A practical insurance mobile app development strategy should prioritize the capabilities that remove friction from the existing claims journey.
1. Digital first notice of loss: Policyholders can report an incident through the app and provide the information needed to begin the claim.
2. Photo and video capture: The application can guide users through capturing images or video of damage. This information can then be made available to adjusters or automated assessment tools.
3. Document submission: Customers can upload receipts, reports, estimates, identification documents, and other claim-related records.
4. Real-time claim tracking: Customers can see claim status, outstanding actions, appointments, and updates without repeatedly contacting the insurer.
5. In-app communication: Messaging and notifications can keep policyholders and claims teams connected throughout the process.
6. Adjuster workflows: Field personnel can use mobile applications to access claim information, record observations, upload evidence, and update tasks while working outside the office.
7. Integration of APIs: APIs can connect the application with policy administration systems, claims management software, payment systems, document management platforms, repair networks, analytics platforms, and other enterprise applications.
The integration layer is particularly important. An app that simply collects information can create another place for employees to manage data. An app connected to the claims ecosystem can feed that information into the processes already used to manage and resolve claims.
How Mobile Apps Improve Claims Processing
The strongest case for mobile claims applications is not simply that they provide another customer channel. They can help insurers capture information closer to the point of loss and move it into the claims process sooner.
Consider a property damage claim. A policyholder can report the loss, provide photographs, upload supporting documents, and answer questions through the application. The connected claims platform can then receive the information and initiate the appropriate workflow.
From there, the insurer can use rules and automation to determine the next step. A claim may be assigned to the appropriate team; a notification may request missing information, or an adjuster may be given access to submitted evidence.
This creates several practical improvements, such as:
Faster information capture: Claims teams receive information electronically instead of waiting for paper documents or manually entering details from phone calls, which can help reduce avoidable delays in the claims cycle.
Lower administrative effort: Data entered through the application can populate connected systems, reducing duplicate data entry, document handling, and routine follow-up.
Greater adjuster productivity: Adjusters can access claim information, photographs, documents, and updates through connected workflows, giving them more time to focus on assessment and customer interactions.
Better claim visibility: Policyholders and employees can access current claim information through appropriate interfaces, reducing the need for repeated status inquiries.
More consistent workflows: Integrated claims systems can apply business rules and trigger tasks based on claim characteristics, helping teams handle similar claims through consistent processes.
Improved customer experience: Faster information exchange, clearer status updates, and fewer manual handoffs can reduce friction for policyholders throughout the claims journey.
“Recent research also points to persistent problems with fragmented and unclear claims experiences. Its analysis of nearly 4,000 property-and-casualty insurance customer responses found that claims experience can strongly influence customer loyalty, reinforcing the need to reduce friction during the process.” - Deloitte
Mobile technology does not remove the need for claim professionals. Complex or disputed claims may still require investigation, negotiation, and judgment. The role of digital tools is to reduce avoidable administrative work and give those professionals better information.
Mobile Claims Apps and AI-powered Insurance
AI can extend the capabilities of insurance claims software, but AI-assisted processing and fully automated processing should not be treated as the same thing.
1. AI-assisted claims processing
In an AI-assisted workflow, the technology analyzes information and provides recommendations, summaries, classifications, or other outputs while a claims professional remains responsible for the relevant decision.
Examples include:
- Analyzing photographs to support damage assessment
- Extracting information from uploaded documents
- Summarizing claim histories or adjuster notes
- Identifying potential fraud indicators
- Prioritizing or routing claims
- Suggesting next actions to an adjuster
- Generating customer-service responses for review
This model is particularly useful when the technology can reduce information-processing work without removing the human judgment required for the decision.
2. Fully automated claims processing
Fully automated or straight-through processing goes further. Here, a claim that meets predefined conditions can move through several stages without manual intervention.
For example, an insurer could establish rules for a simple claim with predictable characteristics. If the policy is active, the loss falls within defined coverage parameters, required information is present, automated checks return acceptable results, and the damage falls within an approved threshold, the system may be able to progress the claim toward settlement automatically.
“Insurers are already applying AI to claims management and describes capabilities that evaluate information such as adjuster notes, damage images, text submissions, documents, and claim histories.” - McKinsey
This distinction is important when implementing insurance claims software. AI should be introduced according to the type of decision being made, the quality of available data, and the level of human oversight required. The objective is to automate appropriate work while keeping experienced claims professionals involved where judgment matters.
Security and Compliance Considerations
A claims application can handle sensitive information, including personal details, financial information, photographs, location data, and, depending on the insurance product, health information. Security therefore needs to be considered throughout the application's architecture and integrations.
An insurance mobile app should therefore be designed around requirements such as:
- Strong authentication and authorization
- Encryption for data in transit and at rest
- Secure API communication
- Role-based access controls
- Audit trails for sensitive actions
- Secure document and media storage
- Appropriate consent and data-use controls
- Secure integration with claims and policy systems
- Monitoring for suspicious activity
The exact compliance requirements will vary by jurisdiction, insurance product, and data being processed. Development teams should establish those requirements before defining the application's architecture.
How to Develop an Insurance Claims Mobile App
Effective insurance app development starts with understanding the claims process that the application needs to support.
A practical approach is to work through the process in four stages:
1. Map the claims journey: Identify where policyholders and claims teams currently experience delays. This may include first notice of loss, document collection, damage assessment, adjuster assignment, communication, or settlement.
2. Map the technology ecosystem: Determine which systems the application needs to exchange information with, such as claims management software, policy administration systems, CRM platforms, document management systems, payment services, and analytics or AI platforms.
3. Select opportunities for automation: Not every step needs automation. Notifications, document routing, status updates, and certain forms of claim assignment may be suitable for workflow automation. AI can then be considered for tasks such as document extraction, image analysis, summarization, and claim prioritization.
4. Build security and testing into the development process: Testing should cover authentication, permissions, APIs, integrations, offline scenarios, error handling, auditability, and the behavior of automated features. This helps ensure that the mobile experience works as part of the broader claims system, rather than as an isolated application.
A phased approach can also make implementation more manageable. An insurer may begin with digital first notice of loss and claim tracking before expanding into document automation, field adjuster capabilities, AI-assisted assessment, and additional integrations.
The future of mobile insurance claims
The next stage of mobile claims is less about adding more features to an app and more about connecting the app to the wider claims ecosystem.
“Research describes a model in which mobile applications, claims platforms, third-party data, analytics, AI, and human claims professionals work together across the claims journey. In this model, simpler claims can move through increasingly automated workflows, while complex cases continue to depend on human expertise.” - McKinsey
That makes digital claims processing an architectural challenge as much as a mobile development project. The customer-facing application needs to connect with the systems that store policy and claim information, the workflows that move claims forward, and the tools that support employees in making decisions.
For insurers, the practical goal is a claims experience in which information can be captured once, moved securely between connected systems, and used at the right stage of the process. Mobile applications can provide the front end for that experience, while claims management software, automation, analytics, and AI support what happens behind it.
Disclaimer:
This content has been made available for information purposes only. Views and opinions expressed in this content are those of the individual author only and do not necessarily represent the opinions and views of Chetu. Chetu, and its representatives, make no representation or warranty of any kind, express or implied, regarding the accuracy, adequacy, validity, reliability, availability, or completeness of any information of this content. Under no circumstances shall Chetu, or its representatives, have any liability to you or any loss or damage of any kind incurred as a result of the use of this content or reliance on any information provided in this content. Your use of this website and your reliance on any information on this content is solely at your own risk.
About Chetu:
Founded in 2000, Chetu empowers businesses with AI and digital transformation solutions, supporting startups, SMBs, and Fortune 5000 companies. We deliver end-to-end software solutions backed by global digital intelligence and industry expertise. Our customized software delivery model and one-stop-shop approach span the full technology spectrum. Headquartered in Sunrise, Florida, Chetu operates 13 locations across the U.S., Europe, and Asia.
See more at: Chetu Blogs
Share


Limited Time Offer for a Free E-Book

Suggested
Reading
Read our blogs on automation strategies, technology and business solutions.